MORTGAGE ARTICLES
Mortgage Options During Divorce or Separation: What You Should Know If you’re going through—or considering—a divorce or separation, you may not realize that there are mortgage solutions specifically designed to help one party keep the home . For many people, the family home is their largest asset and where most of their equity is tied up. In situations like this, a spousal buyout program can allow one person to refinance the property and buy out the other party’s share—often up to 95% of the home’s value . This option can work whether you want to keep the home or your former partner does. What Is the Spousal Buyout Program? The spousal buyout program is a refinancing option that allows one owner to purchase the other owner’s share of the property as part of a separation or divorce settlement. In some cases, it can also be used to pay off jointly held debts, as outlined in a legal agreement. Below are some of the most common questions about how the program works. Is a finalized separation agreement required? Yes. Lenders require a signed and finalized separation agreement that clearly outlines how assets and debts are to be divided. This document is essential for approval. Can the funds be used for renovations or personal debts? No. Funds from a spousal buyout can only be used to: Buy out the other owner’s share of equity Pay off joint debts specifically listed in the separation agreement They cannot be used for renovations, personal loans, or unrelated expenses. How much equity can be accessed? The maximum amount available is the amount required to: Buy out the other party’s agreed-upon share of equity Pay off any joint debts listed in the agreement This amount cannot exceed 95% loan-to-value . What is the maximum loan-to-value allowed? The maximum loan-to-value is the lesser of : 95%, or The remaining mortgage balance plus the required buyout and joint debt payout The property must be the primary owner-occupied residence . Do all parties need to be on title? Yes. All individuals involved in the buyout must currently be registered on title. Your solicitor will confirm this through a title search. Does this only apply to married or common-law couples? No. While commonly used for married or common-law couples, the program may also apply to siblings or friends who jointly own a property and need one party to exit the mortgage. These cases are typically reviewed on an exception basis and require insurer approval. If no separation agreement exists, the purchase contract must clearly outline the buyout terms. Is a full appraisal required? Yes. A physical, on-site appraisal is required to confirm the property’s value before the mortgage can be finalized. Final Thoughts This overview covers some of the most common questions about mortgage options during separation or divorce, but every situation is different. Working with an independent mortgage professional gives you access to multiple lenders, specialized programs, and unbiased advice—so you can clearly understand your options and choose what’s best for your future. If you’re navigating a separation and need guidance around keeping or selling the home, feel free to connect anytime. All conversations are handled with discretion and confidentiality, and I’d be happy to walk you through your options.
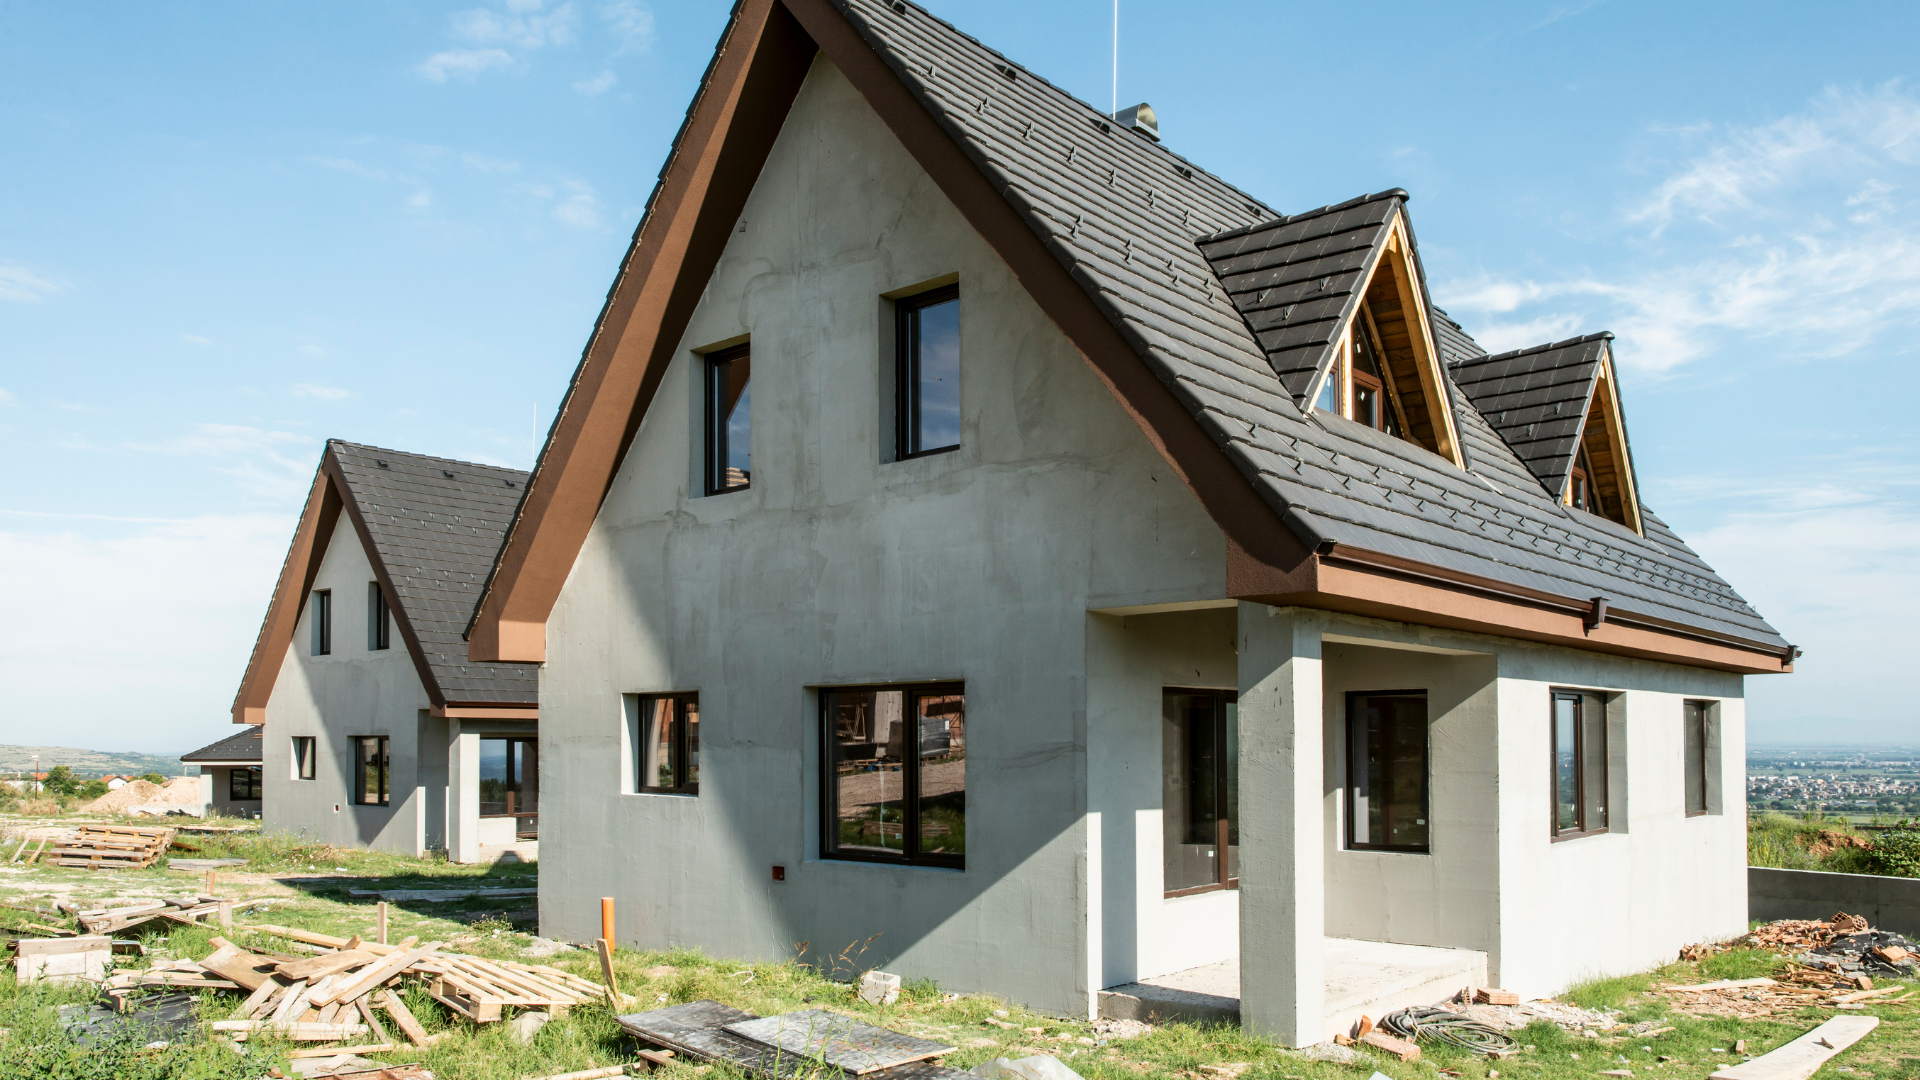
Why More Mortgage Options Matter—Especially for Assignment Purchases One of the biggest advantages of working with an independent mortgage professional is access to choice. Instead of being limited to one lender and one set of products, mortgage brokers work with multiple lenders—each with different guidelines, risk tolerances, and mortgage solutions. That flexibility becomes especially valuable when your situation doesn’t fit neatly into a “standard” box. A great example of this is purchasing new construction through an assignment contract . Why Assignment Purchases Can Be Challenging Assignment purchases are often viewed as higher risk by traditional lenders. Rather than declining these deals outright, many lenders quietly make them difficult by adding layers of conditions, restrictions, or uncertainty. This can lead to delays, frustration, or financing falling apart late in the process. The Good News There are lenders—available exclusively through the broker channel —that have clear, favourable policies for assignment purchases. With the right lender and proper planning, these transactions are absolutely doable. Typical Financing Requirements for Assignment Purchases While every situation is unique, many lenders that allow assignment financing look for the following: Standard purchase qualification, including income verification, credit, and down payment Assignments accepted at either the original purchase price or current market value Minimum 620 credit score , with no prior bankruptcies or consumer proposals The full down payment must come from the purchaser —seller incentives cannot be used Required Documentation To secure financing, lenders typically require: The original purchase agreement signed by all parties The MLS listing (if applicable) The assignment agreement signed by the builder, original purchaser, and new buyer Any side agreements outlining changes to the purchase price A full appraisal to confirm value This list isn’t exhaustive, but it highlights that while assignment purchases require more coordination, they are very achievable with the right lender and guidance. Final Thoughts Assignment contracts can open doors to great opportunities—but only if your financing supports the transaction. This is where access to multiple lenders and specialized policies makes a real difference. If you’re considering purchasing new construction through an assignment, or if you’d like to explore more traditional purchase options, feel free to connect anytime. I’d be happy to walk you through the mortgage products available and help you choose an option that doesn’t limit your financing possibilities.
How Mortgage Payment Frequency Affects What You Pay Over Time You’ve probably heard the saying that there are two certainties in life: death and taxes. When it comes to your mortgage, there’s really just one certainty—you’ll repay what you borrow, plus interest. What is flexible, though, is how often you make your mortgage payments. And that choice can have a meaningful impact on how quickly you pay down your mortgage and how much interest you pay over time. The Six Mortgage Payment Frequencies Most lenders offer the following payment options: Monthly – 12 payments per year Semi-monthly – 24 payments per year Bi-weekly – 26 payments per year Weekly – 52 payments per year Accelerated bi-weekly – 26 payments per year Accelerated weekly – 52 payments per year Standard Payment Frequencies The first four options are designed to align with how you get paid. For example: Paid monthly? Monthly mortgage payments may make sense. Paid every two weeks? Bi-weekly payments can align nicely with your cash flow. With these standard options, regardless of how often you pay, the total amount paid over the year is the same —it’s simply divided into more frequent payments. What Makes “Accelerated” Payments Different Accelerated payments work differently—and this is where the real savings happen. With accelerated bi-weekly or accelerated weekly payments, you’re paying a slightly higher amount each time. That extra money goes directly toward reducing your mortgage principal, which lowers the interest you’ll pay over the life of the mortgage. A Simple Example Let’s assume a $1,000 monthly mortgage payment: Monthly: $1,000 once per month = $12,000 per year Semi-monthly: $500 twice per month = $12,000 per year Bi-weekly: $1,000 × 12 ÷ 26 = $461.54 every two weeks = $12,000 per year Accelerated bi-weekly: $1,000 ÷ 2 = $500 every two weeks = $13,000 per year With accelerated bi-weekly payments, you effectively make two extra payments per year without having to think about it. Those extra payments reduce your principal faster, which lowers interest costs over time. Accelerated weekly payments work the same way—you just make smaller payments more frequently. Why This Matters Long Term While it’s difficult to calculate exact savings due to variables like interest rates, terms, and amortization changes, maintaining an accelerated payment schedule over the life of your mortgage can reduce your amortization by up to three years and save a significant amount of interest. The Bottom Line Accelerated payments are a simple, automatic way to lower your overall cost of borrowing—without needing to make lump-sum payments or drastically change your budget. If you’d like to see how different payment frequencies would impact your mortgage specifically, feel free to reach out anytime. I’d be happy to walk through the numbers with you and help you choose the option that fits your goals.
You’ve outgrown your current home. It no longer fits your life, so moving makes sense. And you’re not interested in juggling two properties. Selling first and buying something new feels like the right move. Ideally, you want possession of the new home before leaving the old one. That overlap makes moving easier, reduces stress, and gives you time to paint, renovate, or settle in before the boxes arrive. But there’s a common challenge. What if the down payment for your next home is tied up in the equity of the one you’re selling? That’s where bridge financing comes in. How bridge financing works Bridge financing temporarily unlocks equity from your current home once it has a firm sale . It bridges the gap between selling your existing property and purchasing your next one, allowing you to use that equity toward your down payment. What about competitive markets? In a hot market, a strong offer often means a larger deposit . If you don’t have that cash sitting in your account, but you do have equity, a deposit loan can help you compete with confidence. The non-negotiable requirement To qualify for bridge financing or a deposit loan, your current home must have a firm, unconditional sale . No firm sale = no bridge or deposit loan. Lenders need certainty to calculate available equity and manage risk. Bottom line A firm sale is the key that unlocks bridge financing and deposit loans. If you’re planning a move and want to understand how these options could work for you, let’s talk. I’m always happy to walk you through your options and help you plan your next step with confidence.
Financial setbacks happen. Bankruptcies and consumer proposals are more common than most people realize—and they don’t define your future. Going through one doesn’t mean homeownership is off the table forever. It simply means lenders want to see that you’ve taken control, learned from the past, and built a stronger financial foundation moving forward. What lenders look at after a bankruptcy or consumer proposal How long it’s been since your discharge Your discharge date matters. For lenders, this is your reset point. There’s no law that says you must wait a specific amount of time before applying for a mortgage, but the longer your track record after discharge, the stronger your application becomes. What matters most is how responsibly you’ve managed your finances since then. Your credit rebuild Re-establishing credit is critical. After discharge, most people start with a secured credit card and use it consistently and responsibly. To be considered fully re-established, lenders typically want to see: Two active trade lines At least two years of clean payment history Credit limits of around $2,500 on each No late or missed payments Your down payment or equity The more money you can put down—or the more equity you have when refinancing—the lower the risk for the lender. A stronger down payment often opens the door to better terms and more lender options. Your debt service ratios Lenders will also look closely at how much of your income goes toward housing and other debts. The stronger your income relative to your monthly obligations, the easier it is to qualify. Conventional vs. insured mortgage options To access the most competitive mortgage products, lenders typically want to see: At least two years plus one day since discharge Fully re-established credit Minimum down payment requirements met Mortgage insurance in place if your down payment is under 20% (through CMHC, Sagen, or Canada Guaranty) Total debt obligations generally not exceeding 44% of your gross income Alternative lending options Not every situation fits neatly into a bank’s box—and that’s where alternative lending can help. Independent mortgage professionals work with both traditional and alternative lenders, including those who specialize in complex financial situations. These lenders look at the full picture: equity, income stability, and your plan moving forward. While rates and terms may not be as competitive as prime lending, alternative financing can be an effective short-term solution—especially if you need a mortgage before your credit is fully rebuilt. Let’s talk about your next step Whether you’re planning ahead for the best possible mortgage—or need a solution sooner rather than later—there are options available. If you’d like help mapping out a clear path forward, reach out anytime. I’d be happy to review your situation and help you build a plan that gets you back into homeownership with confidence.
Retirement doesn’t always mean a mortgage-free life anymore. And that’s okay. Between higher home prices, rising living costs, and longer life expectancy, many Canadians are choosing to retire with a mortgage or refinance later in life to create more flexibility. The goal isn’t perfection. It’s having options that actually support the life you want to live. If you’re thinking about how a mortgage fits into your retirement years, you’re not alone—and you’re not out of options. Why work with an independent mortgage professional? Because retirement financing is not one-size-fits-all. Unlike a single bank, an independent mortgage professional can look across multiple lenders and solutions to find what truly fits your income, equity, and long-term plans—not just what one institution offers. Mortgage options available in retirement Traditional Mortgage Solutions Many retirees still qualify for standard mortgages. Pension income, investment income, and other retirement sources can often be used to support an application. If you have good equity and solid credit, this is often the lowest-cost option. Reverse Mortgages For homeowners 55+, a reverse mortgage can unlock tax-free equity from your home with no monthly payments required. There’s no income verification or medical questions, making it a helpful option for those who want to improve cash flow while staying in their home. Home Equity Line of Credit (HELOC) A HELOC allows you to access your home equity as needed and only pay interest on what you use. Many retirees appreciate the flexibility and like consolidating income and expenses in one place. Private Financing Sometimes life throws a curveball. If timing, income, or credit create challenges, private financing can act as a short-term bridge. It’s not usually the first choice, but it can provide solutions when traditional lenders can’t. If you’re approaching retirement—or already there—and wondering how your mortgage fits into the picture, let’s talk. A clear plan can make retirement feel a lot more secure and a lot less stressful.
What Online Mortgage Calculators Can—and Can’t—Tell You Online mortgage calculators are everywhere—and on the surface, they seem like a no-brainer. You plug in some numbers, and out pops what you can “afford.” Simple, right? Not quite. While the math itself is correct, the story behind those numbers is often misleading. Mortgage qualification isn’t just about numbers—it’s about context, risk, and lender policy. And that’s where calculators fall short. The Numbers Are Accurate—but the Picture Isn’t An online calculator can show you what a payment might look like at a given interest rate, or how making extra payments could reduce your amortization. That’s useful information! But when it comes to mortgage qualification , calculators don’t account for the many variables that lenders consider, such as: Your credit history and score Employment type (salary, self-employed, contract) Outstanding debts and monthly obligations Assets, savings, and down payment source The property type and location you’re buying Lenders evaluate all these factors through their internal risk models. That means two people entering the exact same numbers into a calculator could receive very different results when they actually apply for a mortgage. Why Online Calculators Can Mislead You When you see a “How much can I afford?” or “Mortgage Qualification” calculator online, it’s easy to treat the result as fact. But these tools don’t know your financial story—they only crunch the data you enter. A calculator can’t predict how a lender views your risk, how new mortgage rules apply to your file, or how things like spousal support, car loans, or variable income will impact approval. In short: calculators estimate payments, not qualification . Use Calculators the Right Way Don’t get us wrong—online calculators still have value. Use them to explore different “what-if” scenarios: How do payments change with different down payment amounts? How would a rate increase affect affordability? What if you added $100 a month to your payments? These tools are great for helping you understand your comfort zone. Just remember: they’re a starting point, not a green light. The Real First Step: Get a Pre-Approval If you’re serious about buying a home, skip the guesswork and get a mortgage pre-approval . It’s quick, free, and gives you real-world clarity on what you can afford. A pre-approval looks at your full financial picture—income, credit, debts, assets—and provides a framework for your purchase price, payment range, and rate options. It’s the only way to get a reliable answer to the question, “What can I really afford?” Final Thoughts Online calculators are convenient, but they can’t replace expert advice. Think of them as a starting point, not a solution. A professional mortgage broker can interpret the numbers, navigate lender policies, and tailor your financing strategy to your actual situation. If you’d like help understanding your true buying power—or want to get pre-approved with confidence— reach out anytime . I’d be happy to walk you through your options and help you make sense of the numbers.
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.
Going Through a Divorce? Don’t Let Your Credit Take the Hit Divorce is stressful enough without adding financial fallout to the mix. Between lawyers, paperwork, and emotional strain, it’s easy to overlook how a separation can impact your credit. But your financial future depends on protecting it now—because long after the dust settles, a damaged credit score can linger. Here are a few smart steps to help keep your credit strong and your finances steady as you move forward. 1. Take Control of Joint Debts When it comes to joint debt, both parties are equally responsible—no matter what your divorce agreement says. If your ex misses a payment on an account with your name attached, your credit takes the hit too. Go through all joint credit cards, loans, and lines of credit. Wherever possible: Close joint accounts to stop future shared use. Transfer balances to the person responsible for repayment. Notify lenders in writing of any changes to account ownership. Once everything is updated, pull your credit report after three to six months to confirm all joint accounts have been closed and reporting correctly. Mistakes happen—stay proactive to prevent surprises later. 2. Open Your Own Bank Accounts Separation means financial independence, and that starts with your own banking. Open a new chequing account in your name only and redirect your pay deposits and bill payments there. At the same time, close any joint bank accounts and change passwords on existing online banking and credit profiles. Even in peaceful separations, shared access can cause confusion—or conflict. Protect yourself by ensuring your money and information are secure. 3. Start Building Credit in Your Name If most of your past credit was tied to your spouse’s name, now’s the time to establish your own. Apply for a small personal credit card or secured credit product . Use it sparingly and pay it off in full each month. This helps you build a solid individual credit history, setting the stage for future goals like buying a home, refinancing, or starting fresh financially. 4. Keep an Eye on Your Credit Monitor your credit report regularly for errors or unexpected changes. You can request free reports from both major credit bureaus in Canada— Equifax and TransUnion —once a year. Tracking your credit isn’t just about catching mistakes; it helps you see your progress as you rebuild your financial independence. Final Thoughts Divorce can be emotionally draining, but protecting your credit doesn’t have to be complicated. By taking a few careful steps now—closing joint accounts, building credit in your name, and monitoring your reports—you’ll safeguard your financial health and gain peace of mind as you start your next chapter. If you’d like personalized guidance on managing credit during or after a divorce, reach out anytime. I’d be happy to walk you through your options.